
The Golden Visa in an Age of Global Uncertainty — and Why Greece Is Entering 2027 from a Position of Strength
For more than a decade, Greece’s Golden Visa has been described primarily as a residency-by-investment programme.
That definition is technically correct.
But by 2026, it is no longer sufficient.
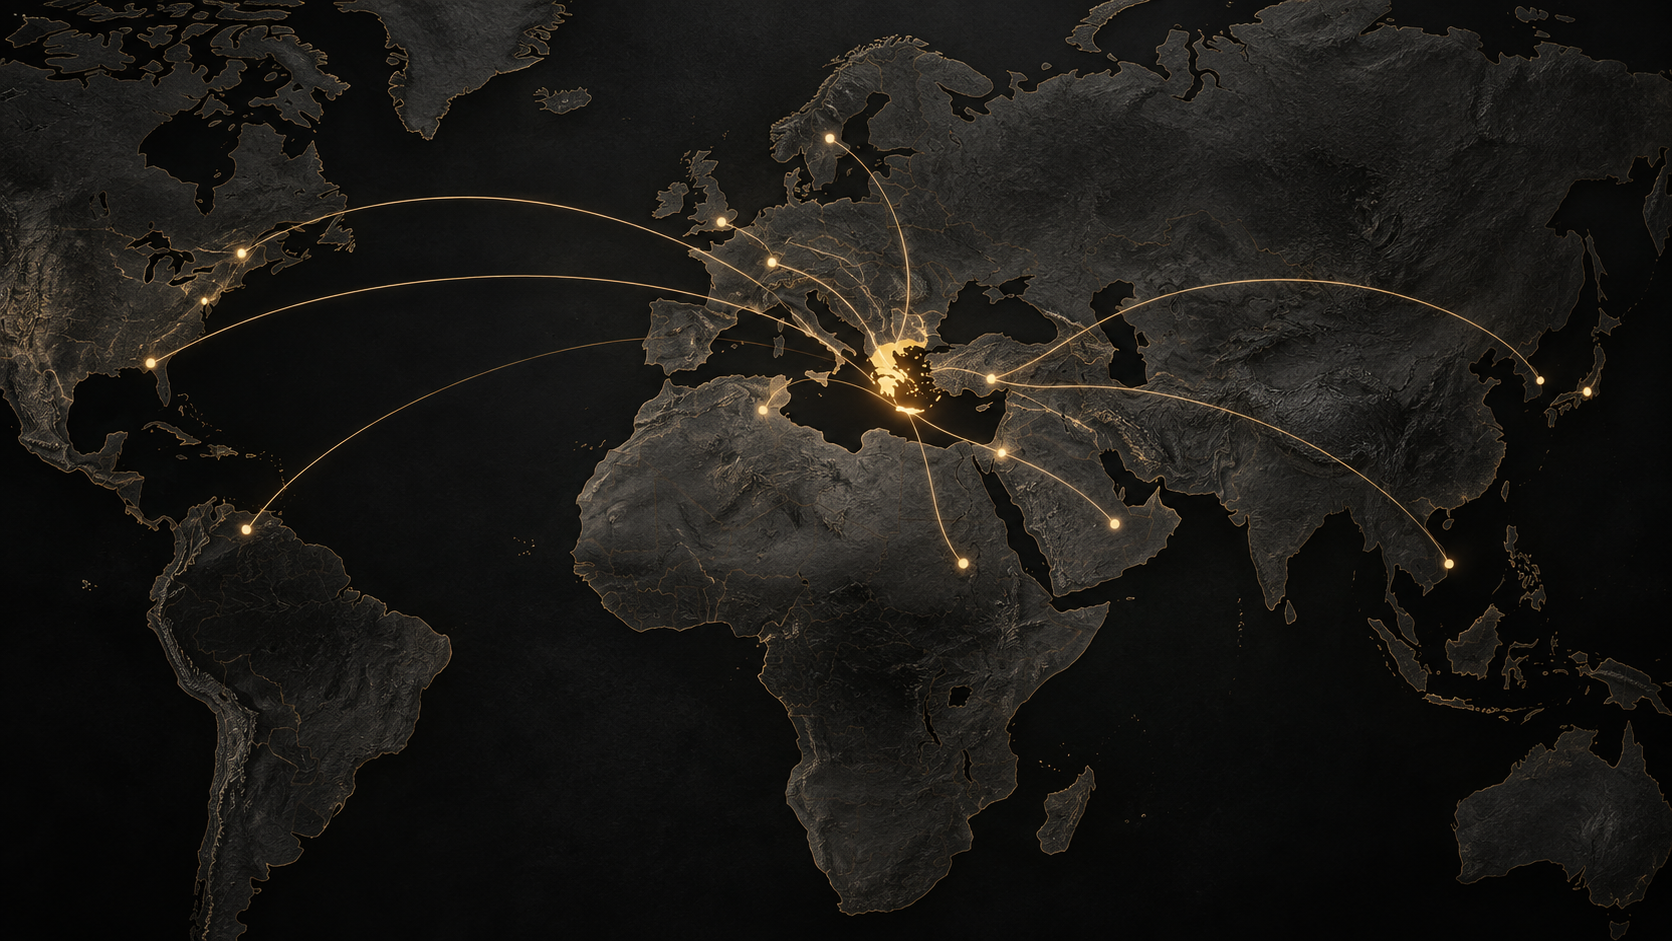
The programme has increasingly become part of a much larger global movement of capital, families and personal risk management.
Chinese investors are reassessing an economy that is still growing but no longer at the speed of previous decades.
Families across the Eastern Mediterranean and the Middle East are living with heightened geopolitical uncertainty.
Turkish investors have faced years of inflation and currency pressure.
American interest in European residency has grown noticeably.
And internationally mobile families increasingly view a second residence not simply as a lifestyle purchase, but as a form of geographic diversification.
Against that background sits Greece.
A European Union country.
A member of the euro area.
Part of the Schengen Area.
A country whose economy is still significantly less developed than those of many northern and western European states — yet which has been growing faster than the euro-area average.
This combination is important.
It helps explain why Greece continues to attract investors from countries whose economic, political and security circumstances could hardly be more different.
The common denominator is not nationality.
It is optionality.
The Golden Visa Is Becoming a Global Risk-Diversification Product
The traditional interpretation of investment migration is straightforward:
an investor contributes capital and receives residence rights.
But the motivation behind that decision has evolved.
For many families today, the value of a second residence is not determined solely by whether they intend to relocate immediately.
It can provide an additional jurisdiction.
An additional home.
Access to another part of the world.
An alternative educational environment for children.
A place for retirement.
A hedge against instability.
And, perhaps most importantly, the ability to make a decision later rather than being forced to make one during a crisis.
This helps explain the diversity of demand that Greece has experienced.
Enterprise Greece reported that 8,879 new Golden Visa residence permits were approved in 2025, compared with 4,535 in 2024 — an increase of approximately 95%.
The largest relative increases were recorded among investors from Turkey, Israel, China, Iran and the United States.
These countries do not share one economic story.
But each illustrates a different reason why internationally mobile capital may value Greece.
China: From Rapid Expansion to Wealth Diversification
Chinese investors remain the largest single nationality within Greece’s Golden Visa programme.
By mid-2026, Chinese nationals still accounted for almost half of initial investor permits recorded under the programme.
This should not be interpreted simply as Chinese capital “leaving China”.
China remains one of the world’s largest and most sophisticated economies.
But its economic environment has changed significantly.
China’s economy grew by 5% in 2025. The IMF’s July 2026 country projection put 2026 growth at 4.6%. Its 2025 Article IV review also highlighted weak domestic demand, the prolonged property-sector adjustment, population ageing and weaker productivity as structural challenges.
For higher-net-worth families, such an environment can increase the appeal of international diversification.
That does not necessarily mean abandoning domestic assets.
It can mean adding something else.
A European property.
A euro-denominated asset.
An international education option.
A residence permit.
And a second geographic base for the family.
Greece historically offered this combination at a relatively accessible level of capital compared with many established Western European markets.
That helps explain why Chinese participation has remained structurally important even as the Golden Visa rules themselves have changed.
The Middle East and Eastern Mediterranean: When Residence Becomes Security
The reasons are different for investors from Israel, Iran, Lebanon and the wider Middle Eastern region.
Here, personal and family security can play a much greater role.
The region has experienced a period of exceptional instability. The 2026 conflict in the Middle East and the resulting energy-price shock affected transport, businesses and economic confidence well beyond the immediate region, as reflected in the European Commission’s spring forecast.
Greek Golden Visa data had already begun reflecting increased participation from the region.
In 2025, permits issued to Israeli investors rose by more than 90%, while Iranian participation also increased substantially. Greek market reporting linked part of this demand to conflict, instability and the desire among some families to establish an alternative base in a nearby European country.
Geography matters here.
Athens is not on the other side of the world from the Eastern Mediterranean.
For many regional investors, Greece offers Europe without requiring them to disconnect completely from their existing lives, families and businesses.
That geographic proximity gives the Greek programme a characteristic that cannot be reproduced simply by lowering an investment threshold.
Greece is simultaneously European and Mediterranean.
For investors from the region, that can be extremely valuable.
Turkey: Geography, Inflation and European Optionality
Turkey has emerged as one of the largest sources of Golden Visa demand.
Enterprise Greece reported that Turkish investor permits increased dramatically in 2025, with Turkey becoming the programme’s second-largest source market.
The motivations again differ from those of Chinese investors.
Greek market analysis has associated Turkish demand with a combination of inflation, currency pressure, capital preservation, proximity and access to the Schengen area.
The geographic relationship is unique.
An investor does not necessarily have to choose between life in Turkey and life in Greece.
For someone based in Istanbul or western Turkey, a Greek residence can form part of the same regional lifestyle and business network.
That makes the Golden Visa something more flexible than traditional emigration.
It can function as a second base rather than a permanent departure.
America: The Rise of the European “Plan B”
Perhaps one of the most interesting changes in recent years has been the increase in American interest.
Historically, the United States was not one of the dominant nationalities within Greece’s Golden Visa programme.
That is changing.
Enterprise Greece identified the United States among the nationalities showing the largest relative increase in 2025. This supports the direction of the trend, although approved permits, valid permits, applications and property enquiries must be treated as separate measures.
It would be too simplistic to attribute this exclusively to American politics.
Different American buyers have different motivations.
Some are Greek-Americans reconnecting with family origins.
Some want a European lifestyle.
Some are purchasing holiday property.
Some are diversifying assets internationally.
And investment-migration advisers increasingly describe a segment of US demand as seeking a European “Plan B” — a place where residence rights exist even if there is no intention to relocate immediately.
The point is not whether an investor believes the United States is becoming better or worse.
The investment logic is diversification.
A wealthy family may own equities, bonds, companies and property in several locations.
Increasingly, geographic residence itself is treated in the same way.
Why Greece?
Global uncertainty alone cannot explain Greece’s success.
Instability may encourage investors to look abroad.
It does not determine where they go.
Greece has developed several characteristics that make it particularly interesting.
One of them is a rare economic combination:
Greece remains below the economic level of much of Western and Northern Europe, while simultaneously growing faster than much of the euro area.
According to Eurostat, Greece’s GDP per capita in purchasing-power terms stood at approximately 68.4% of the EU average in 2025.
Germany, Denmark, the Netherlands, Sweden and several other northern and western European economies remained at or above the EU average.
Historically, such a gap was viewed as a weakness.
From an investment perspective, however, it can also represent room for convergence.
Greece is not Germany.
It is not the Netherlands.
It is not Denmark.
Its productivity, incomes and economic output per person remain lower.
But this also means that Greece is still moving through a different stage of economic development.
The European Commission currently expects Greek GDP to grow approximately 1.8% in 2026, compared with around 0.9% for the euro area, and approximately 1.6% in 2027, compared with 1.2% for the euro area.
Greece therefore combines two characteristics rarely found together:
the legal and institutional framework of the European Union, and the economic convergence potential of a country still catching up with richer European economies.
For long-term investors, that combination deserves attention.
Greece Is No Longer the Greece of the Debt Crisis
It is also important to understand how much the country’s investment profile has changed.
The Greek economy remains imperfect.
Housing affordability is a serious problem.
Productivity needs further improvement.
Public debt remains high.
Structural reform remains important.
But international investment has returned on a scale that would have been difficult to imagine during the sovereign-debt crisis.
The Bank of Greece reported foreign direct investment flows of approximately €6 billion in 2024, equivalent to around 2.5% of GDP, the second-highest level in two decades.
More than 45% of those flows were directed toward real estate, with the Bank of Greece specifically noting that investor activity was partly influenced by changes to Golden Visa thresholds.
The European Commission now expects investment to remain an important support for Greek growth, assisted by EU funds and continued structural development.
That changes the Golden Visa story.
The programme is no longer operating inside an economy desperately searching for capital.
It is operating inside an economy increasingly capable of choosing what kind of capital it wants.
From €250,000 Everywhere to a More Selective System
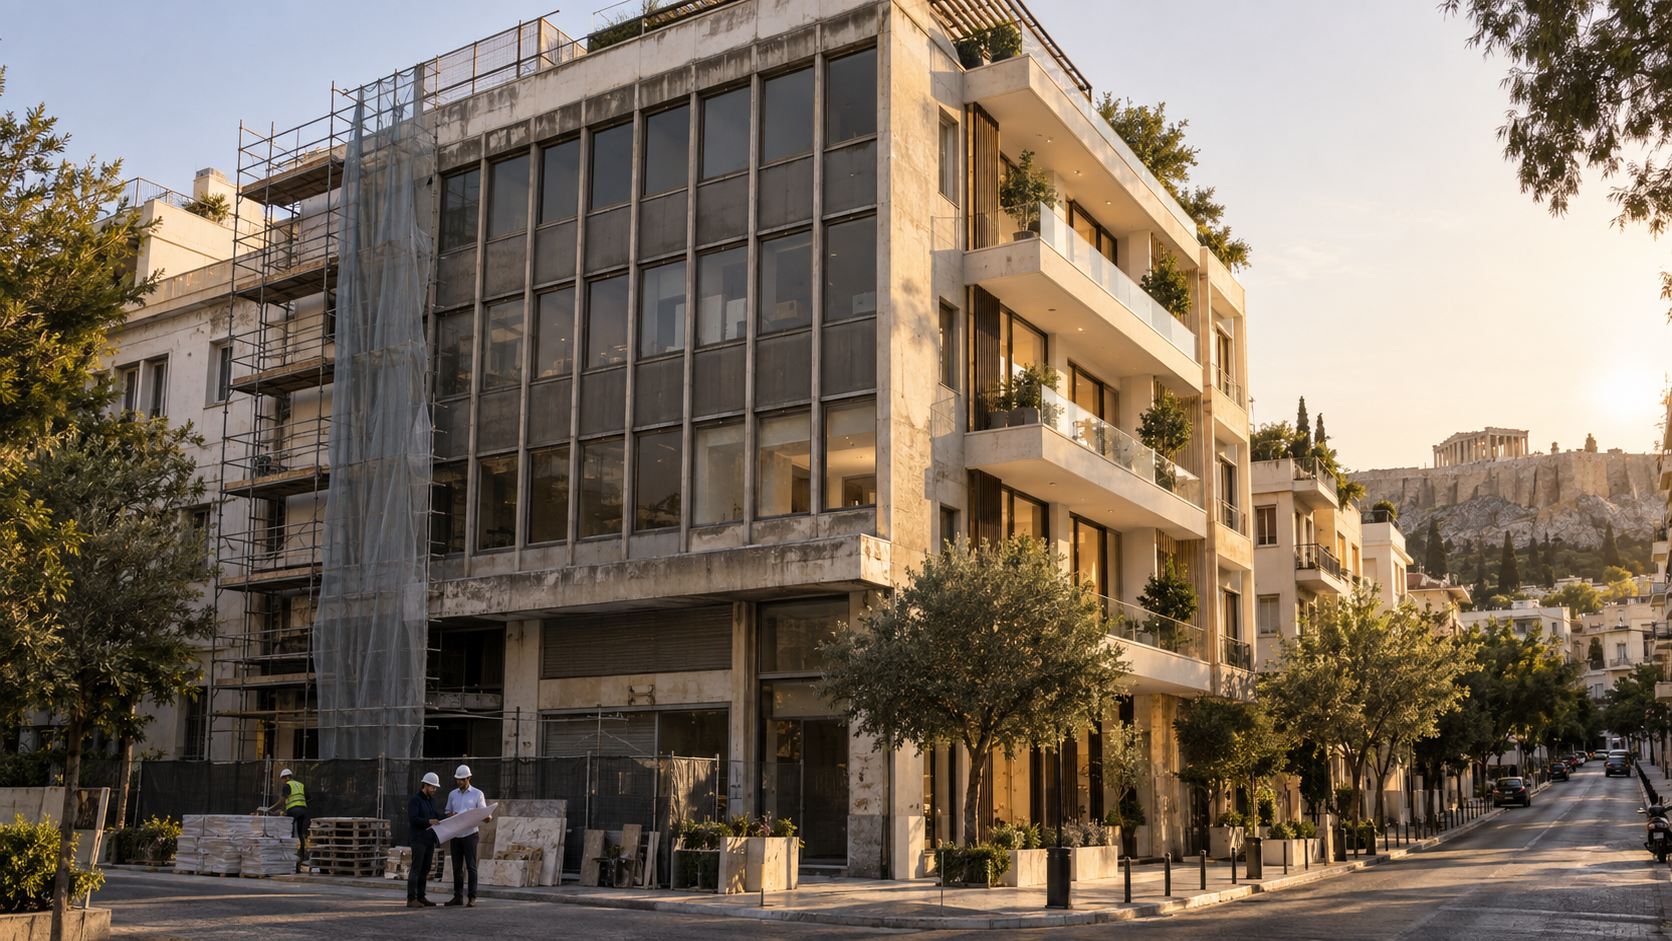
This is precisely what recent Golden Visa reforms demonstrate.
The programme has not disappeared.
Instead, Greece has made it more selective.
Higher thresholds apply to conventional property acquisitions in major markets: broadly €800,000 in Attica, Thessaloniki and certain islands, and €400,000 in other areas under the applicable framework.
At the same time, Greece preserved a €250,000 investment framework for qualifying commercial-to-residential conversions and certain listed-building investments.
The official Greek administrative registry still confirms the €250,000 change-of-use framework and describes the investor permit as valid for five years.
This is important.
The state is no longer treating every property investment in exactly the same way.
Investment that competes directly for existing residential stock is being treated differently from investment that may convert obsolete commercial space into housing.
The programme is therefore evolving from a simple capital-attraction mechanism into a more targeted investment policy.
The New 15% Residential Transfer Tax Fits the Same Pattern
The economic measures announced by the Greek government on 7 September 2026 provide another example.
The government announced a measure under which the property transfer tax for specified residential purchases by affected third-country buyers would rise from 3% to 15%. The enacted text, commencement rules and buyer-specific application should be confirmed before any transaction.
Including the municipal surcharge, the effective rates discussed by the government are approximately 3.09% and 15.45%, respectively.
The measure specifically targets residential property. The government states that it does not apply in the same manner to professional premises, land or other categories of real estate.
Its stated policy rationale is the pressure that additional residential demand can place on prices and residents’ access to housing.
The fiscal significance is also clear.
The government’s own estimates show approximately €100 million of additional annual public revenue from 2027 onward from the measure.
This creates a dual policy effect:
higher fiscal contribution from certain foreign residential demand, and a stronger price signal discouraging excessive competition for existing housing.
At the same time, investment structures that create new economic activity — including qualifying conversions — remain part of the Golden Visa framework.
That is increasingly the logic of Greek policy.
Not less investment.
More differentiated investment.
What Actually Happens in 2027?
This point is important because there is already confusion in the international market.
As of 25 September 2026, the official procedures reviewed for this article remain active and continue to provide five-year investor residence permits under the applicable conditions. Those sources show no 31 December 2027 sunset date.
The accurate, dated conclusion is therefore:
The current official framework remains operational, and the reviewed sources show no announced 31 December 2027 termination date.
This describes the official material available on the review date; it is not a guarantee that policy will remain unchanged.
What is changing in 2027 is the fiscal and regulatory environment surrounding certain property purchases.
The government’s fiscal table estimates additional revenue from the announced residential transfer-tax measure from 2027 onward. That estimate should not be read as a substitute for the enacted commencement and scope provisions.
Housing measures are being tightened.
The role of conversions is becoming more important.
And policymakers are increasingly distinguishing between capital that merely acquires existing housing and capital that creates productive economic activity.
Investors should therefore not confuse policy evolution with programme termination.
The Real Advantage of Greece Is Not One Tax Rate or One Investment Threshold
Investment migration programmes inevitably change.
Thresholds rise.
Taxes change.
Property rules are revised.
Governments respond to housing pressures.
Any investor who chooses a country simply because one number appears attractive today may misunderstand the nature of a long-term investment decision.
Greece’s deeper advantage is structural.
It sits at the intersection of several global trends.
A Chinese family may be seeking diversification.
A Turkish investor may be protecting purchasing power.
An Israeli or Iranian family may value geographic security.
An American family may want European optionality.
An entrepreneur may see economic convergence.
A retiree may see quality of life.
Different motivations arrive at the same destination.
That is why Greece’s Golden Visa should not be viewed simply as an immigration product.
It is increasingly a reflection of the way global families think about risk.
From “Golden Visa” to Geographic Diversification
The world that created the Greek Golden Visa in 2013 was very different from the world of 2026.
Then, Greece was recovering from an extraordinary domestic economic crisis.
Today, uncertainty is much more global.
Geopolitical conflict affects energy and transport.
China is moving from its historical high-growth model toward a slower and more complex economic structure.
American investors are increasingly international in their property and residence decisions.
The Eastern Mediterranean remains strategically sensitive.
And wealthy families are increasingly unwilling to place every part of their economic and personal future in one jurisdiction.
Against that backdrop, Greece offers something difficult to express through a single financial calculation:
European stability with economic convergence potential.
It is not as wealthy as Northern Europe.
That is part of the opportunity.
It does not have the scale of the United States or China.
That is part of its character.
It is not insulated from global geopolitical risk.
No European economy is.
But it combines European institutions, the euro, the Mediterranean, a recovering investment environment and a residency programme that — despite repeated reforms — remains operational.
This is why international attention has persisted.
And it is why 2027 should not be viewed simply as another deadline.
It should be viewed as the beginning of the next phase.
A phase in which Greece continues to welcome international capital, while becoming increasingly selective about how that capital enters the economy and what economic value it creates.
The future of the Golden Visa may therefore be less about finding the lowest possible investment threshold.
It may be about something considerably more important:
finding the right European jurisdiction in an increasingly uncertain world.
For many international families, Greece continues to be part of that conversation.
Principal sources reviewed
- Enterprise Greece, “News in brief — February 2026,” reporting 2025 Golden Visa approvals and nationality trends.
- Greek Government, detailed economic measures announced at the 90th Thessaloniki International Fair, September
- Greek National Registry of Administrative Public Services (Mitos), Golden Visa change-of-use and listed-building procedures, updated August and September
- Greek Housing Policy Portal, EUR 250,000 change-of-use and listed-building investment routes.
- Eurostat, Key figures on Europe — 2026 edition .
- European Commission, Spring 2026 Economic Forecast and Greece country forecast, 21 May
- International Monetary Fund, China 2025 Article IV consultation and July 2026 country projection.
- Bank of Greece, Annual Report 2024 .
Related Santheos Resources
- Greece Golden Visa Expert Column
- Official Greece Golden Visa Guidance
- From Empty Offices to New Homes: Greece’s EUR 250,000 Conversion Framework
- Lei Chen — Policy Research, Data and Market Analysis
This article provides general policy, economic and market analysis. It is not legal, tax, immigration, investment or property-specific advice. Rules, procedures and taxes may change, and eligibility and transaction consequences require current professional review.