
“Guaranteed rent” can sound simpler than ordinary letting: buy the property, receive an agreed payment and leave the administration to someone else. But the phrase does not explain who owes the money, how much the owner receives or what happens if the arrangement ends early.
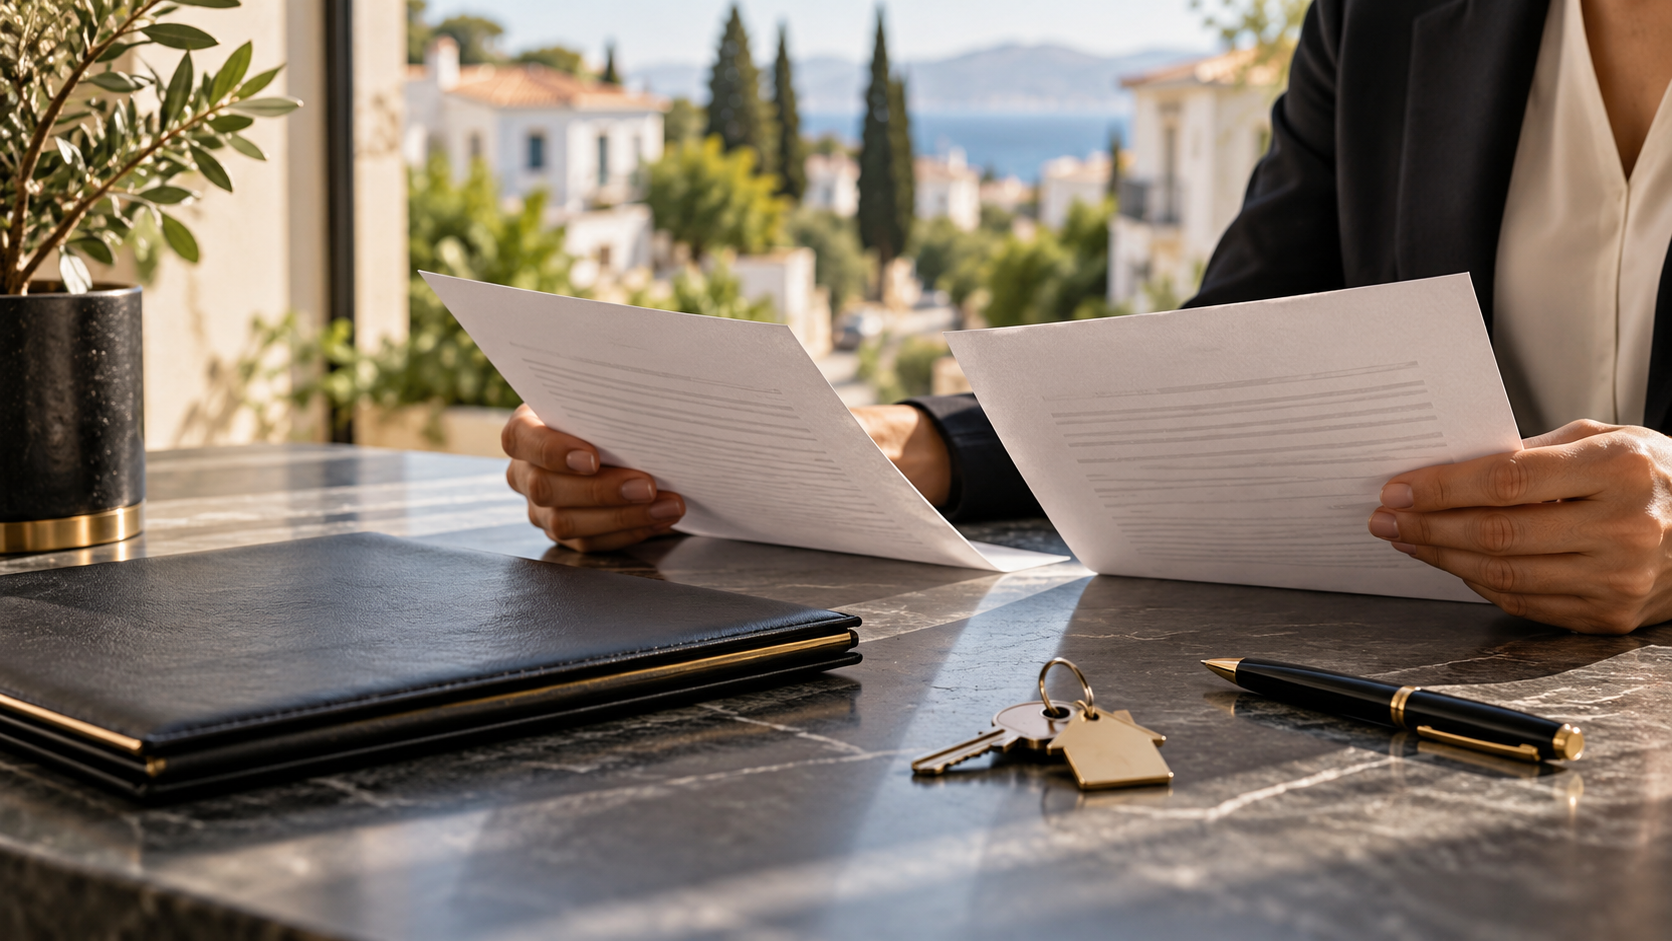
Examine the written agreement as a separate commercial commitment. The following questions are editorial due-diligence suggestions, not statutory contract requirements or a conclusion about an individual contract’s enforceability.
Identify who owes the payment
Is the payer the seller, a tenant, an operating company or another entity? Request the exact legal name and the agreement creating the obligation. Ask the lawyer which documents bind the payer and whether the sales illustration forms part of the signed agreement.
A company commitment is not automatically a bank guarantee, insurance policy or secured obligation. Ask the lawyer what financial information is available, whether security exists and how the owner could enforce the commitment. The payment figure does not establish the payer’s ability to perform.
Define the percentage and its starting date
Does the percentage apply to the purchase price or the full acquisition outlay? Is it before management fees, insurance, repairs and income tax? Does payment begin at completion, handover, occupancy or another event?
For illustration only, 4% of EUR 250,000 equals EUR 10,000 annually. If the owner pays additional expenses, that is not the final cash return. This arithmetic does not establish that such an offer exists or is suitable for a particular property.
Read the exclusions
Check treatment of vacancy, late rent, repairs, access problems, unfinished work and periods when the home cannot be occupied. Identify owner obligations that might suspend payment. Ask who approves repairs and whether expenses can be deducted from the next transfer.
Prepare a schedule showing who bears each cost, who decides and which documents support a deduction. Do not assume that a fixed payment transfers every ownership risk to the operator.
Confirm the operating model
The proposed use must suit the property and applicable rules. Where Golden Visa eligibility matters, have an independent lawyer review the arrangement before commitment. A revenue forecast cannot establish that a letting model is permitted.
Avoid switching between long-term letting, visitor accommodation and owner occupation as though they had identical conditions. The contract should describe the actual arrangement being offered.
Understand how the arrangement ends
Review renewal, notice, termination, possession, existing occupiers and the condition in which the property must be returned. What happens if the owner sells, the manager changes or the payer stops trading?
A practical downside question is what documents, cash reserve and alternative management arrangements the owner would have if payments stopped. Ask the lawyer to explain the dispute process without assuming immediate recovery.
Compare complete proposals
Compare a fixed-payment offer and ordinary management on the same acquisition budget and lawful use. Include expenses and risks under each. Keep tax advice separate: AADE identifies Greek-source property income as relevant to non-resident taxation; the contractual label alone does not establish tax treatment.
Request the contract, payer identity, payment schedule, cost allocation, exclusions, security and exit provisions. Ask Santheos what is actually offered for the specific unit. This checklist does not state that Santheos offers guaranteed rent or a particular return.
General information, not investment, legal or tax advice. Obtain independent review of the actual agreement.